Analysis 7 min read
Our second information day, in Ferney‑Voltaire.
On 3 November, even more of you came to Ferney‑Voltaire to find out about Swiss franc mortgages. The next two days take place in Annecy, on 18 and 24 November.
Hello Justice, editorial team

Contents
On Tuesday 3 November 2026, we held our second information day on Swiss franc mortgages in Ferney‑Voltaire, with ACTIVE AVOCATS, a firm of the COGEP AVOCATS group. Even more of you came to meet us than at the information day of 28 October, and we thank you for it. The next two days take place in Annecy, on Wednesday 18 and Tuesday 24 November: book your place now.
A growing team.
We now have more than 600 live cases, taken on since 2024. To keep up with this volume, our team and the firm’s are growing again. Maître Vincent DURAND, a partner at ACTIVE AVOCATS, and Valentin PETITCLERC, President and founder of Hello Justice, led the talks with the lawyers present. Between two presentations, the firm met borrowers in one‑to‑one meetings, by appointment.
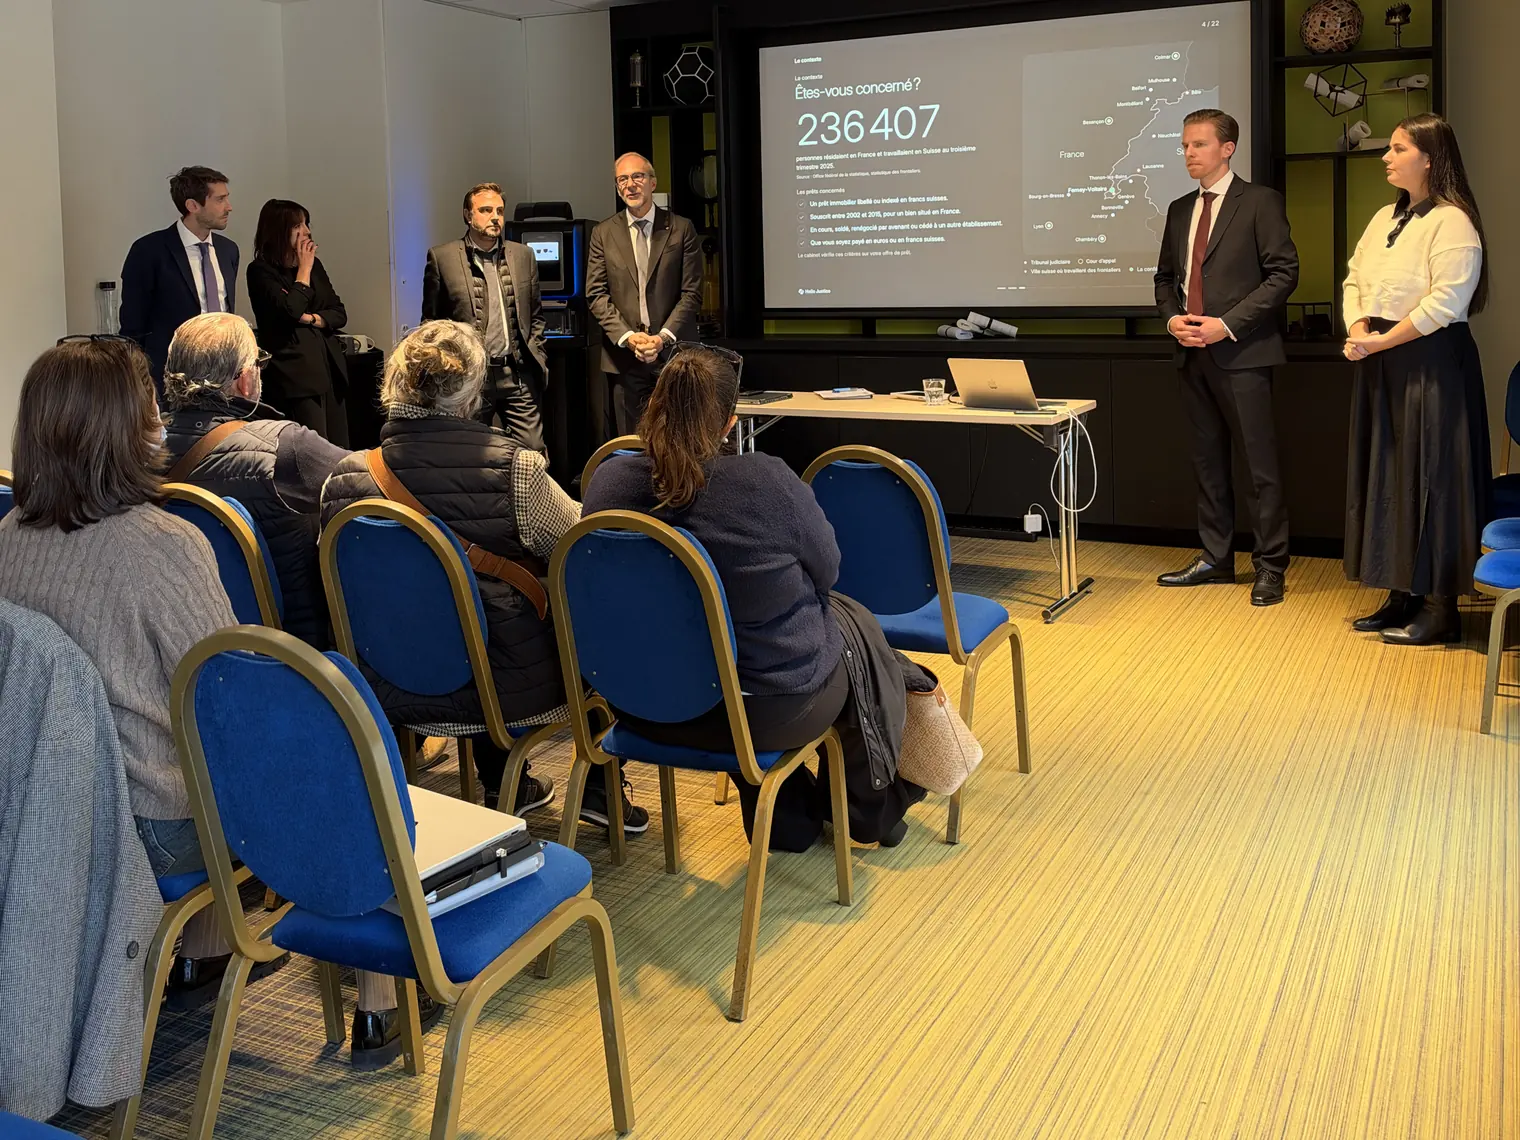
An information talk in Ferney‑Voltaire on 3 November 2026.
The programme of each talk.
Each talk lasts 45 minutes: 30 minutes of presentation, then 15 minutes of questions. It starts with the loans concerned, denominated in or indexed to Swiss francs and taken out between 2002 and 2015 for a property in France. The firm also reviews a loan that has been repaid, renegotiated by amendment or transferred to another lender, whether you are paid in euros or in Swiss francs. In the border area, these loans were very widely distributed: more than 230,000 people today live in France and work in Switzerland Source [1]. The lawyers then answer three questions.
Does being paid in Swiss francs remove the currency risk?
Neither a salary in Swiss francs nor the currency of the loan settles the question on its own. On 9 July 2025, the Cour de cassation handed down two rulings, recent case law liable to change Source [2]. In ruling no. 24-19.647, it assesses the currency risk over the whole term of the loan. It takes into account the borrower’s status as a cross‑border worker and the location of the property in France, and affords them protection against unfair terms. In ruling no. 24-18.018, handed down the same day, it upholds the clause of a 2014 loan: the bank had provided an offer and two signed notices. The court therefore assesses the transparency of the contract on the documents provided at signature, case by case.
Does an unfair term lead to the refund of the sums paid?
Proceedings can involve three claims, and each follows its own reasoning. A claim to have a term declared unfair is not time‑barred Source [3] Source [4]. In principle, restitution of the sums paid must be claimed within five years of the decision that finds the term unfair Source [5]. The bank may, however, show that the borrower knew, or could reasonably have known, of the unfairness before that decision Source [6], according to recent case law, liable to change. A claim against the bank for failing to inform the borrower is time‑barred after five years, from actual knowledge of the failure and its possible consequences Source [7]. Knowing that the exchange rate has moved is not the same as knowing that a term is unfair. Our article on the time limit for bringing a claim sets out these rules.
What are the financial consequences of an unfair term?
A term held to be unfair is treated as if it had never been written. Two outcomes are then possible: the loan recalculated in euros, or the agreement annulled. Recalculated in euros, the loan reveals the extra cost of the exchange rate. Annulled, it ceases to exist: the bank returns what it has taken, you return the capital you received, and you no longer owe the outstanding capital. No overall refund is automatic: each claim must be proved. The Hello Justice algorithm recalculates each instalment at the official European Central Bank rate for the day it is debited. It then checks the result against the lines of your bank’s repayment schedule, and the firm relies on this calculation to quantify your claim.
The one‑to‑one meeting.
For 15 minutes, in complete confidentiality, one of the three lawyers from the firm present that day meets you. You show them your loan and the documents that come with it, and you ask your questions. This one‑to‑one meeting is free, and you book it when you register.
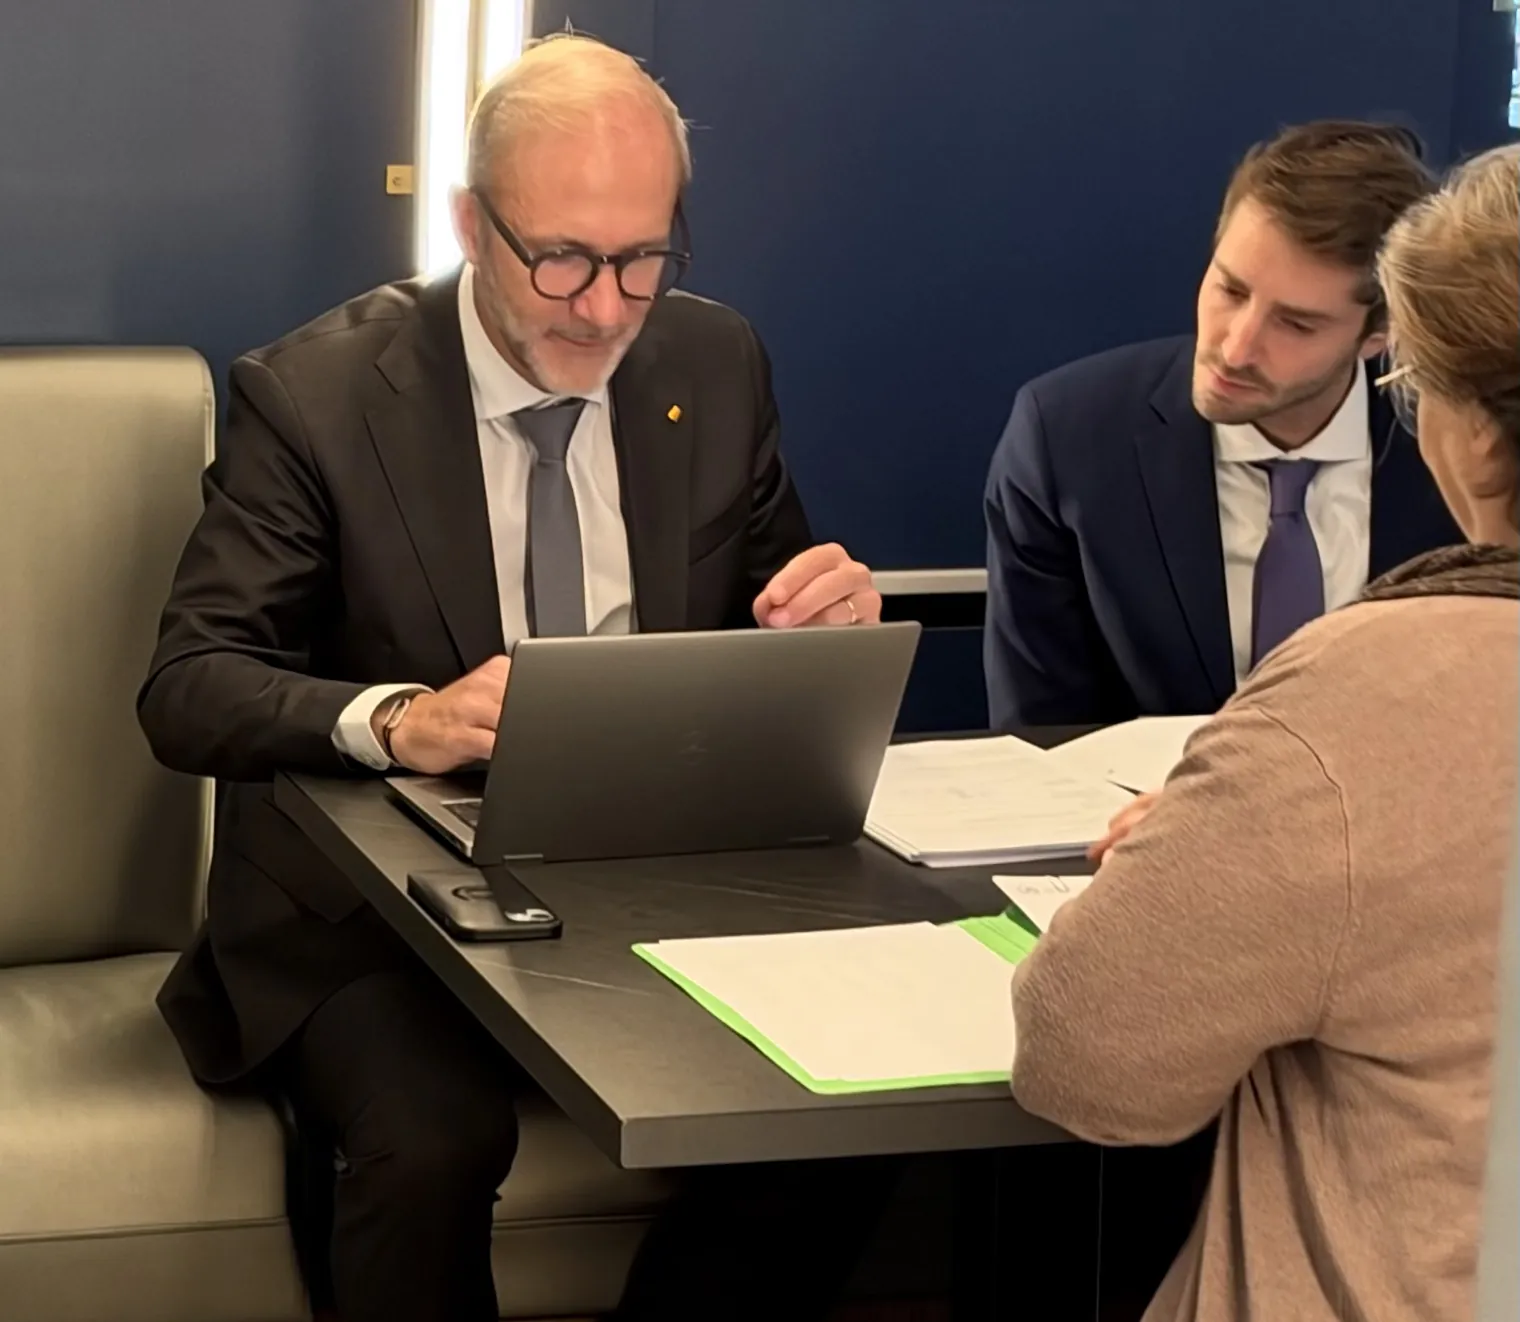
A one‑to‑one meeting in Ferney‑Voltaire on 3 November 2026.
Bring the documents for your loan:
- The loan offer, with its appendices and the notices handed over at signing.
- The repayment schedule: the one in the offer, and any the bank has reissued since.
- The amendments, if there were any. If there never were, simply say so.
- The redemption statement, if the loan has been repaid, or the bank’s letter that stands in for it.
Copies or photos taken with your phone are enough.
Funding your case.
At the end of the talks, Valentin PETITCLERC explained the role of Hello Justice. The principle of litigation funding: Hello Justice covers 100% of your lawyer’s fees and is paid out of the sums recovered, only if the case succeeds.
- Checking your case: free. Submitting your case is free and commits you to nothing.
- Your lawyer’s fees: 100% covered. Whatever the amount you borrowed, at first instance as on appeal.
- Your out‑of‑pocket costs: €300. Paid when your case is opened, if it is accepted, to bring proceedings against your bank. If there is an appeal, only the €225 appeal duty is added.
- If the case succeeds: 14% incl. VAT. On the sums recovered and the saving obtained on your loan. If the case fails, you repay nothing to Hello Justice.
The Annecy information days.
On Wednesday 18 and Tuesday 24 November 2026, we look forward to seeing you at the Hôtel Moxy Annecy, 19 avenue du Rhône. Come and take stock of your loan, even if it has been repaid. Each day features four 45-minute talks on recent case law and borrowers’ rights, as well as 15-minute one‑to‑one meetings with one of the firm’s lawyers. The talks and the one‑to‑one meetings are free, on registration.
| Time | Programme |
|---|---|
| From 11:00 to 12:00 | One‑to‑one meetings with a lawyer, by appointment |
| From 12:15 to 13:00 | Talk (doors open at 12:00) |
| From 13:15 to 14:00 | Talk (doors open at 13:00) |
| From 14:15 to 17:00 | One‑to‑one meetings with a lawyer, by appointment |
| From 17:15 to 18:00 | Talk (doors open at 17:00) |
| From 18:15 to 19:00 | Talk (doors open at 18:00) |
You book online, in three steps:
- Choose your day: Wednesday 18 November or Tuesday 24 November.
- Book a talk, a one‑to‑one meeting, or both, at the time that suits you.
- Enter your details: your confirmation arrives by email, with a file to add to your calendar.
Book early: each talk seats 30 people, guests included, and slots for one‑to‑one meetings are limited. A full talk offers you its waiting list. You can register up to two people with you, a friend, a neighbour or a family member. The Annecy information days page gives directions to the hotel and answers frequently asked questions.
Submitting your claim.
Save time: submit your claim before the day. Answer a few questions about your loan, then add your documents from your phone. Your claim goes to your Hello Justice online space, and the lawyer who meets you one to one can review it beforehand.
Can’t come to Annecy? Open your claim online: ACTIVE AVOCATS reviews your loan offer and checks its dates. Don’t have your documents to hand? Submit your claim without them: a link to your online space arrives by email, and you can finish later without re‑entering anything. The Swiss franc mortgage programme page sets out the steps of the proceedings and how they are funded.
Sources
- 1.Swiss Federal Statistical Office, cross‑border commuter statistics, third quarter of 2025 (new tab) Back to reference 1 in the text
- 2.Cour de cassation, First Civil Chamber, 9 July 2025, no. 24-19.647 and no. 24-18.018, published, recent case law, liable to change (new tab) Back to reference 2 in the text
- 3.Court of Justice of the European Union, 10 June 2021, C-776/19 to C-782/19 (new tab) Back to reference 3 in the text
- 4.Cour de cassation, First Civil Chamber, 30 March 2022, no. 19-17.996, published (new tab) Back to reference 4 in the text
- 5.Cour de cassation, First Civil Chamber, 12 July 2023, no. 22-17.030, published (new tab) Back to reference 5 in the text
- 6.Cour de cassation, First Civil Chamber, 17 September 2025, no. 23-23.629, published (new tab) Back to reference 6 in the text
- 7.French Civil Code, article 2224 (new tab) Back to reference 7 in the text